Noted

Richard Boas, III, Berkshire Hathaway HomeServices HomeSale Realty • January 11, 2022

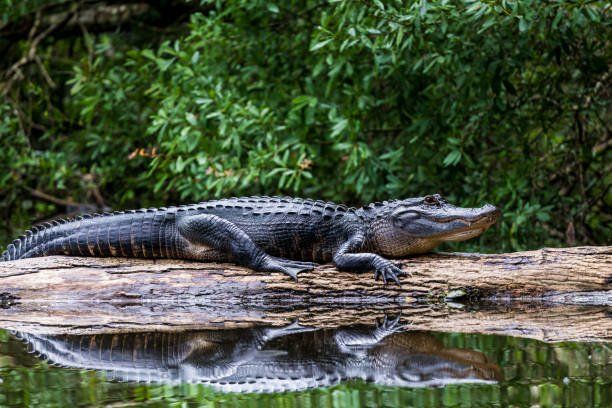
So you're meeting with some buyers for a showing. They're excited because after several letdowns they think they may have finally found their dream home. And you're excited because they're excited. As you walk up to the front door, you take in the beautiful landscaping and the smell of flowers in bloom dotting the side of the driveway. Your buyers then anxiously wait as you wrestle the key from the lockbox. The key ejects, you unlock the door, turn the handle, open the door . . . only to be greeted by an alligator sleeping in a cat castle. You scream, your clients scream, the alligator screams . . . and mayhem ensues.


You quickly flee the home desperately looking up the number on your smartphone for animal control. You ask yourself how an alligator could have possibly gotten into the home as there are no signs of forced entry. This doesn't make any sense. As you wait for animal control to arrive, you call the listing agent to tell them about the horror you have just witnessed. As you frantically explain the situation, the listing agent cuts you off and says, "Oh, that's just Buttons, the sellers' pet alligator. He's harmless." You angrily reply, "Why didn't you tell me the alligator would be present during my showing?!?!?" The listing agent responds, "Well, if you had read the agent notes in the MLS, you would have known that the owners have a nocturnal pet alligator named Buttons who will be present during showings . . . and he also likes belly rubs."


Obviously this scenario is an over-exaggeration, although I'm sure someone somewhere at some point has entered a home with an alligator in it. But the point is, if the buyer agent had simply read the agent notes prior to their showing, they wouldn't be heading home in soiled underwear right now.


Look, I get it. We're all busy. And when you're busy, it's easier to just turn on auto pilot. How many of us have scheduled a showing without knowing anything about the property other than its address? I'm sure we have all done that at some point. I'd be lying if I said I didn't. But as minute a detail as it may seem, double checking the agent's notes section on the MLS listing is something we should all be doing. After all, that section is there for a reason. Whether it be to inform agents of an offer deadline, preferred settlement date for the seller or the fact that the homeowner has a pet alligator named Buttons that likes belly rubs and will be present during showings, those notes often provide important details and insight about a property. Often the agent notes will tell you what you need to know without having to call the listing agent to glean the information from them. But as important as it is to make sure you are checking for notes, it is just as important to make sure that as the listing agent you are leaving them.


We've all had those listings where our phone is ringing off the hook. Agents want to write offers, and they have questions that go with those offers. Have you ever had more than one agent ask the same question about your listing? If only there was a more convenient way to communicate that to them and mitigate the parade coming out of your phone's speakers. Hmmmm. You get my point.


So the next time you schedule a showing, or at the very least before you submit an offer, look up the property on the MLS and see if the listing agent has anything noteworthy to read. You might just save those satin silk undergarments of yours.


Facts, opinions and information expressed in the Blog represent the work of the author and are believed to be accurate, but are not guaranteed. The Lancaster County Association of Realtors is not liable for any potential errors, omissions or outdated information. If errors are noted within a post, please notify the Association. Posts represent the author's opinion and are not necessarily the opinion of the Association.
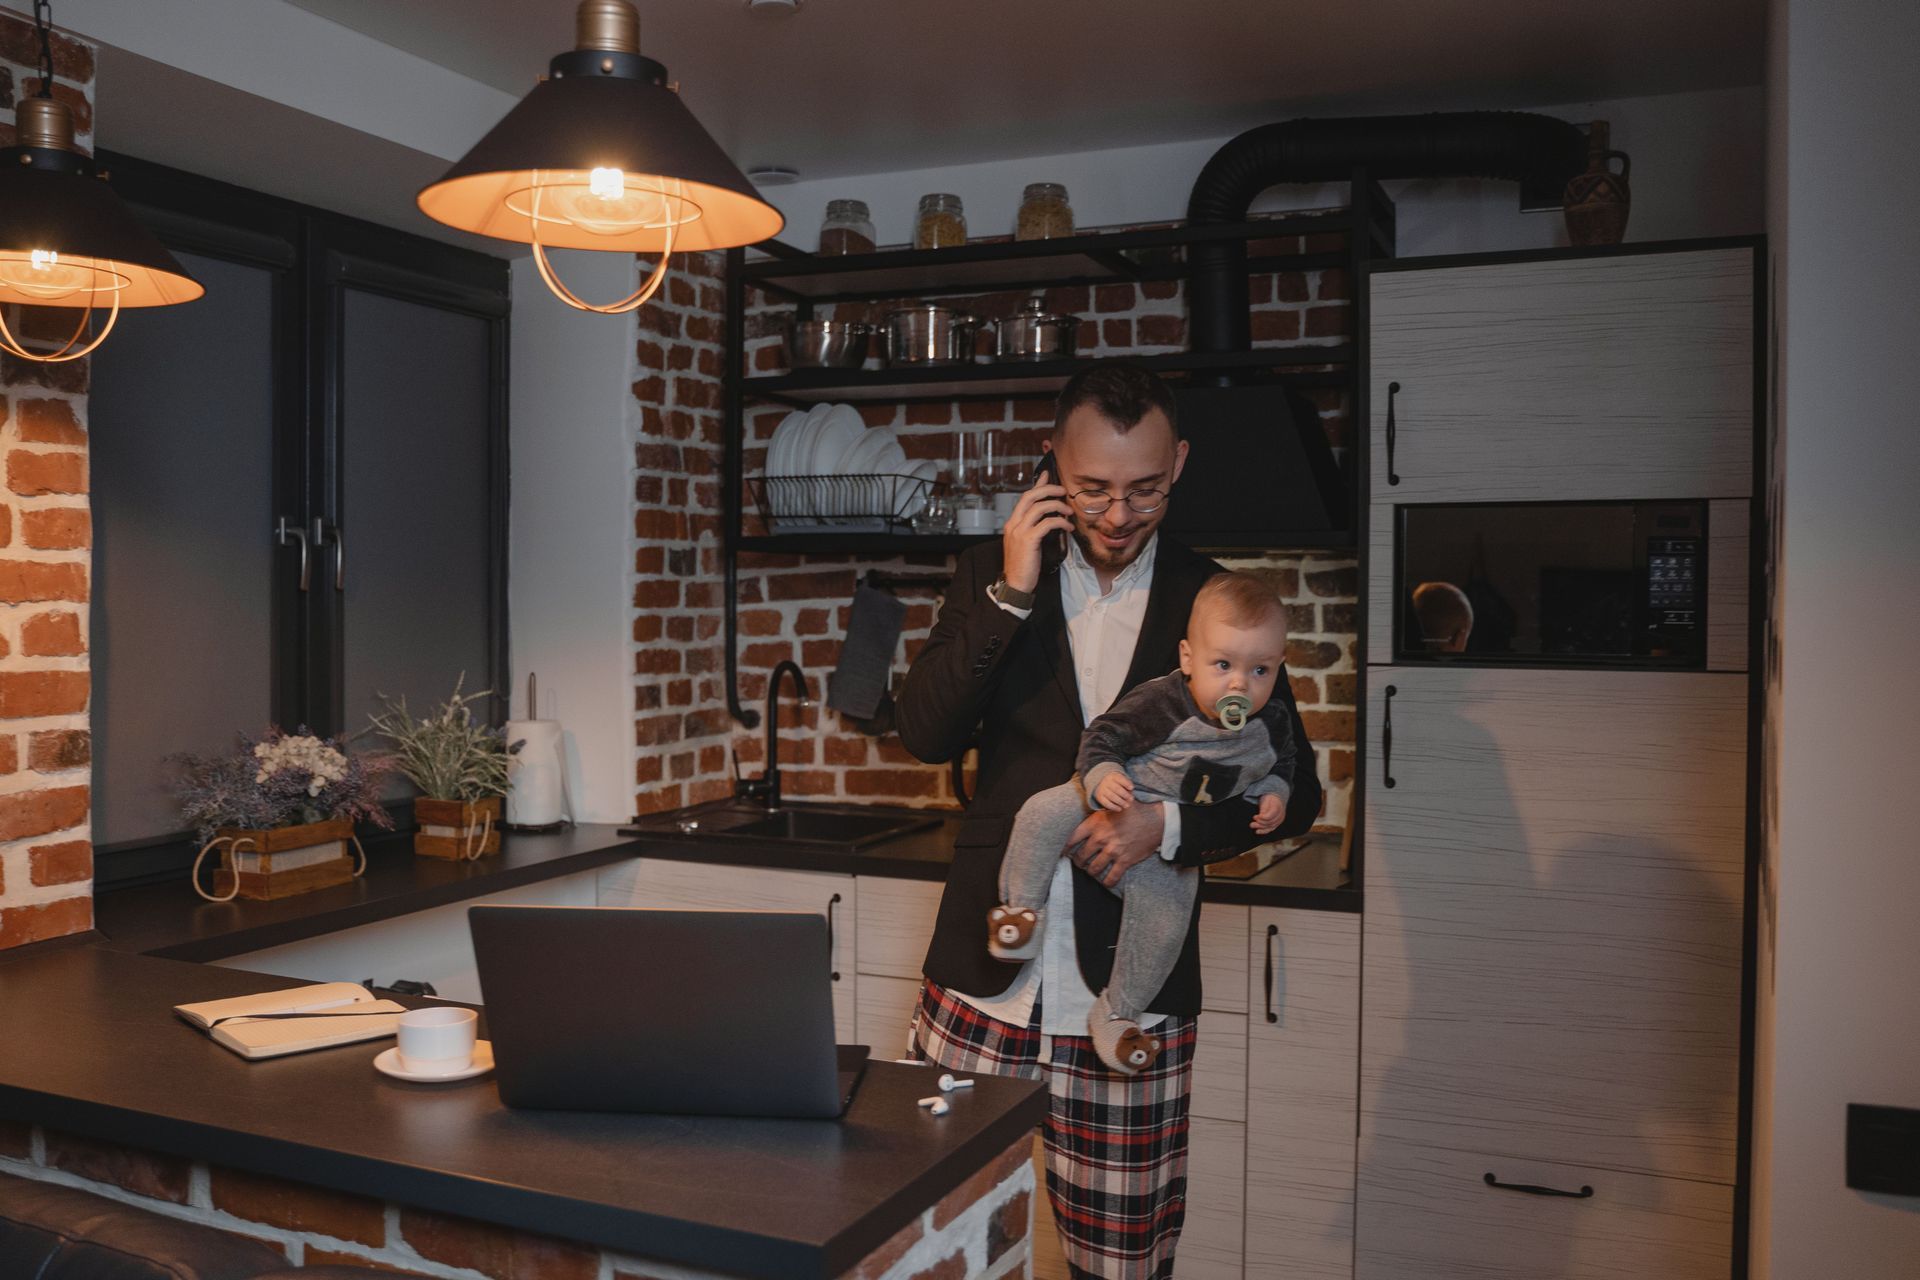
Father holding son showing work life balance as a realtor
By Wayne Angelo, Cross Country Mortgage • September 28, 2026
Work Life Balance
Time blocking as a real estate agent
By Wayne Angelo, Cross Country Mortgage • September 21, 2026
Time Blocking
REALTOR® using the FOREWARN safety app to verify prospective clients and review available public-rec
By Lisa Naples Berkshire Hathaway HomeServices Homesale Realty • September 14, 2026
Learn how REALTORS® can use FOREWARN to verify prospective clients, review available public records, and add another layer of safety before meeting new contacts.
Enhanced Title Insurance: More Protection for Your Home
By Wayne Angelo, Cross Country Mortgage and Bill Stull, Abstract Associates of Lancaster • August 17, 2026
When purchasing a home, buyers often have the option of choosing either a standard or enhanced owner’s title insurance policy. Both policies protect the buyer’s ownership interest in the property, but the enhanced policy provides several valuable protections that go beyond the coverage included in a standard policy. The enhanced policy is available for purchases of one-to-four-family residences and condominiums when the property is being purchased in an individual’s name, rather than in the name of an LLC, corporation, partnership, or other entity. A standard owner’s policy protects against common title problems, including defects, liens or claims against the property, an unmarketable title, and a lack of legal access. The enhanced policy includes those protections while adding coverage for issues that are especially relevant to homeowners, including certain building permit and zoning violations, improper subdivisions, vehicular access problems, and structures that encroach onto the property after the buyer takes ownership. One of the most important added benefits is post-policy forgery protection. A standard policy generally protects against title issues that existed before the buyer purchased the property. The enhanced policy also provides protection if someone later forges the homeowner’s signature or creates a fraudulent deed that clouds the homeowner’s title. With real estate and identity fraud becoming an increasing concern, this protection alone can provide homeowners with valuable peace of mind. The enhanced policy also includes an automatic increase in coverage. The policy amount increases by 10% each year during the first five years of ownership, up to 150% of the original policy amount. This helps the coverage keep pace as the value of the property increases. In Pennsylvania, the enhanced policy is available for a one-time premium that is only 10% higher than the standard owner’s policy premium, with no annual renewal cost. At Abstract Associates, we believe buyers should understand the difference between the two policies before making their decision. For a relatively small additional cost at settlement, the enhanced policy provides broader protection that can continue to benefit the homeowner long after closing.
Top 10 Things People Don’t Understand About Property Insurance
By Raquelle Riti, Bernieri Associates Allstate Insurance • August 3, 2026
Top 10 Things People Don’t Understand About Property Insurance
Reverse Mortgage
By Wayne Angelo & Megan Brogna – CrossCountry Mortgage • July 31, 2026
Most people think of a reverse mortgage as a way for homeowners to access the equity they've built in their current home. While that's certainly true, many Realtors are surprised to learn that a reverse mortgage can also be used to purchase a new home. What Is a Reverse Mortgage? A reverse mortgage, also known as a Home Equity Conversion Mortgage (HECM), is an FHA-insured loan available to homeowners age 62 and older. Instead of making monthly mortgage payments, eligible borrowers can use a portion of their home's equity to eliminate an existing mortgage, establish a line of credit, receive monthly payments, or simply improve cash flow. Borrowers remain responsible for paying property taxes, homeowners' insurance, maintaining the home, and continuing to occupy it as their primary residence. What Is a Reverse Mortgage for Purchase? A HECM for Purchase allows qualified buyers age 55 and older to purchase a new primary residence using a substantial down payment and a reverse mortgage—without the obligation of monthly principal and interest payments.* This program can be an excellent solution for: Buyers looking to downsize. Retirees relocating closer to family. Homeowners moving into a 55+ community. Clients seeking a home that better fits their retirement lifestyle. Buyers who want to preserve more of their retirement savings or investment assets. Instead of paying all cash for a home, buyers can finance part of the purchase through a reverse mortgage, allowing them to keep more of their liquid assets available for future needs. Why Realtors Should Know About This Program A Reverse Mortgage for Purchase can help clients: Increase purchasing power. Improve monthly cash flow. Preserve retirement savings. Purchase a home that better meets their long-term needs. Age in place more comfortably. For many older buyers, this financing option can make the difference between settling for a home and purchasing the one that truly fits their retirement goals. If you work with clients who are 55 or older, a Reverse Mortgage for Purchase may be worth exploring before they write an offer. *Borrowers must continue to pay property taxes, homeowners insurance, maintain the property, and occupy the home as their primary residence. The amount available depends on factors including the youngest borrower's age, current interest rates, and the home's value. Facts, opinions and information expressed in the Blog represent the work of the author and are believed to be accurate but are not guaranteed. The Lancaster County Association of Realtors is not liable for any potential errors, omissions or outdated information. If errors are noted within a post, please notify the Association. Posts represent the author's opinion and are not necessarily the opinion of the Association.
Mid Year Check In Realtor Calendar
By Missy Boots – Realty One Group Unlimited • July 17, 2026
Whew! If you're anything like me, you blinked and somehow July is already halfway over. That also means we've officially crossed the halfway mark of the year. How’s business treating you? Maybe your year is right on track; if so - congrats! If you're holding your breath waiting for your transaction numbers to suddenly align with the goals you set in January, it's time to stop waiting and start resetting. It’s never too late! The beauty of this business is that January doesn't have a monopoly on fresh starts. In real estate, momentum can change surprisingly quickly. One listing can become three referrals. One conversation can lead to a transaction. The second half of the year has the potential to look completely different from the first. The key isn't wishing for a better year. It's changing what you do next. One of the most important mindset shifts an agent can make is to treat their business like a business. Business owners don't simply hope for better results. They create a plan, track meaningful metrics, review what's working, and adjust when needed. Your real estate business deserves the same level of intention. When you start thinking like the CEO of your business instead of just the salesperson in it, your daily decisions begin to change, and so do your results. So where to start? Ask yourself: How many meaningful conversations am I having each week? How consistently am I following up with past clients and leads? Am I asking for referrals? Am I visible in my community and online? Am I blocking time every day for lead generation? Many of us focus on results we can't control: closings, commission checks, or contracts signed. Instead, focus on the activities that create those results. Results lag behind consistent action. If you improve the actions, the numbers usually follow. Choose one or two meaningful goals for the next 3 months. Then identify the handful of weekly actions that move those goals forward. For example: Reach out to 5 people a day. Schedule three coffee meetings with your sphere. Host one open house every weekend. Post valuable content three times a week. Write five handwritten notes every Friday. Consistency beats intensity every time. Your calendar tells the truth. Look back at the last two weeks. How much time was spent on activities that directly grow your business? Admin work is necessary, but revenue producing activities deserve protected time on your calendar. While time blocking is considered a “bad” word to many, being in control of your time allows you to control your business. Schedule lead generation before you schedule anything else. Pick an accountability partner and share your weekly action plan with each other. Commit to checking in regularly and holding one another accountable for following through. Celebrate the wins along the way. When you accomplish the actions you set out to complete, reward yourself, even if it’s just an iced coffee with your accountability partner. Above all, don’t let a negative mind set deter you from forward momentum. Start small. Do the work. Finish big. Here’s to a successful 2026! "Success looks a lot like failure up until the moment you break through the finish line." – Dan Waldschmid “Today is always the most productive day of your week." – Mark Hunter