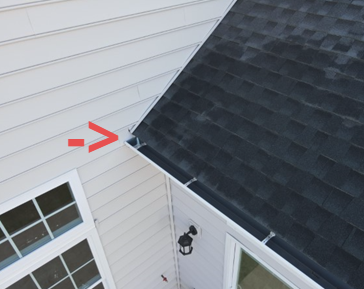
<-- This photo was taken at a newly built home that I recently inspected for the buyer. Kickout flashing was missing at numerous locations. Notice the area just above where the gutter terminates against the siding. Kickout flashing should exist at the roof’s lower edge corner. The home had already passed the township’s code compliance inspection. The code official was actually doing a final walk-through before closing while I was onsite performing the buyer’s home inspection. When I asked the code official about the lack of kickout flashing in these multiple areas, his reply was “I am not too familiar with those requirements.” I was somewhat, understandably, shocked at his response.
Missing Kickout Flashing - A Common Defect
Matthew Steger, ACI • August 16, 2024
When inspecting the exteriors of homes, one of the most common flaws that I seem to find is missing kickout flashing. Roof flashings help prevent water entry into the home. Roof flashings are needed where there are changes in roof angle, at roof penetrations (such as chimneys and plumbing stack pipes), and where roofs join sidewalls or chimneys. In many cases, once a roof covering is installed, the roof flashings are no longer visible.
For homes that have a roof terminating against a lower side wall, kickout flashing is needed. To better illustrate this, think about the end of a gutter terminating laterally adjacent to an exterior side wall. Kickout flashing is needed just above the gutter’s end cap in order to help prevent roof runoff from passing between the gutter’s end cap and the home’s siding. The first 2 photos below are good illustrations of such an area. The lack of proper flashing can allow damage to the siding below this area to occur and may also allow hidden water damage into the adjacent exterior wall below this area. If a gutter terminates against a chimney, kickout flashing should also be installed just above that junction. It’s called kickout flashing because, in essence, as water runs down the roof along a side wall, this flashing kicks the water outwards towards the gutter and away from the gutter’s end cap junction with the siding.
Kickout flashing (also called “sidewall flashing”) has been required since the 2009 IRC (International Residential Code). I’ve seen many photos over the years of contractors called in to repair homes that have extensive water damage, rot, and mold due to years of water runoff onto exterior walls that can be directly linked to missing kickout flashing. The original wording of this flashing requirement in the 2009 IRC was somewhat vague and confusing to some. The wording changed in later code cycles [the IRC is updated every 3 years] to make it perfectly clear to builders, roofers, siding installers, remodelers, home inspectors, code inspectors, etc. that kickout flashing is needed at these areas.
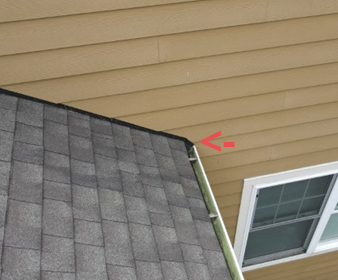
Here’s another example of missing kickout flashing
where a roof and gutter terminate against a cement-board sided exterior wall.
No matter the siding material (vinyl, brick, stone, stucco, cement board, wood, etc.), kickout flashing should be installed at these roof intersections. Some roofers and builders use pre-manufactured kickout flashings (normally made either of plastic or metal) although they can also be fabricated onsite using a large enough (at least, 4” x 4”) piece of sheet metal to conform to the exact angle of the siding and roof intersection.
Even without being able to see above the gutter’s junction with the roof and siding, if you see a lot of water staining or algae on the siding below where a gutter terminates, it’s a good clue that kickout flashing is missing.
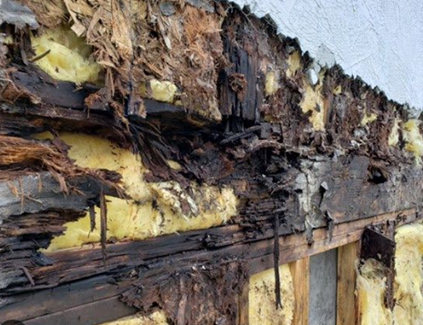
The photo to the right is a good example showing extensive water damage to an exterior wall due to the lack of kickout flashing above this area. Years of water runoff from the roof above this area caused the siding to deteriorate and gradually allow water into the home unbeknownst to the homeowner where extensive framing rot occurred.
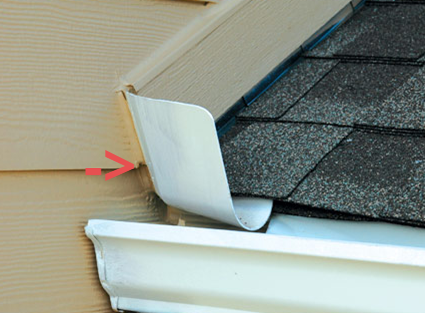
This photo shows proper kickout flashing installed. This is a piece of pre-manufactured plastic kickout flashing. A piece of $20 kickout flashing can mean all the difference between a dry interior wall and extensive siding and exterior wall damage.
-Copyright © Missing Kickout Flashing A Common Defect, Matthew Steger, ACI, 2024. All Rights Reserved.
Facts, opinions and information expressed in the Blog represent the work of the author and are believed to be accurate, but are not guaranteed. The Lancaster County Association of Realtors is not liable for any potential errors, omissions or outdated information. If errors are noted within a post, please notify the Association. Posts represent the author's opinion and are not necessarily the opinion of the Association.
Learn how non-mortgage contingent offers differ from cash offers and what buyers and REALTORS® should know about financing, appraisals, and contract risks.
LANCASTER, PA – Lancaster County's housing market continued to show strength in September 2026, with rising home prices, increased inventory, and stronger year-over-year sales activity, according to the latest statistics from Bright MLS. The median sold price reached $370,000, a 4.2% increase from September 2025. A total of 457 homes were sold during the month, up 6.5% from the previous year. Housing inventory also improved, with 779 active listings, an increase of 17.3% compared to September 2025. New listings rose 4.8% to 551 properties, providing buyers with additional opportunities. “Lancaster County continues to demonstrate the strength and stability of our local housing market,” said Christina Diehl, President of the Lancaster County Association of REALTORS® (LCAR). “The increase in available homes is encouraging for buyers, while continued price appreciation reflects the strong demand for housing in our community.” Homes continued to sell quickly, spending an average of just 20 days on the market, compared to 25 days a year earlier. Properties also sold at an average of 103.1% of their original listing price, demonstrating continued competition among buyers. Year-to-date figures remain positive, with closed sales increasing 2.7% and the median sold price rising 4.3% to $365,000. “As we enter the final months of 2026, we remain optimistic about Lancaster County's housing market,” Diehl added. “While increased inventory offers buyers more choices, demand remains strong. Working with a knowledgeable local REALTOR® continues to be an important advantage for both buyers and sellers.” About the Lancaster County Association of REALTORS® The Lancaster County Association of REALTORS® (LCAR) represents real estate professionals throughout Lancaster County and is dedicated to promoting homeownership, protecting private property rights, and supporting professionalism in the real estate industry.
Work Life Balance
Time Blocking
Learn how REALTORS® can use FOREWARN to verify prospective clients, review available public records, and add another layer of safety before meeting new contacts.

When purchasing a home, buyers often have the option of choosing either a standard or enhanced owner’s title insurance policy. Both policies protect the buyer’s ownership interest in the property, but the enhanced policy provides several valuable protections that go beyond the coverage included in a standard policy. The enhanced policy is available for purchases of one-to-four-family residences and condominiums when the property is being purchased in an individual’s name, rather than in the name of an LLC, corporation, partnership, or other entity. A standard owner’s policy protects against common title problems, including defects, liens or claims against the property, an unmarketable title, and a lack of legal access. The enhanced policy includes those protections while adding coverage for issues that are especially relevant to homeowners, including certain building permit and zoning violations, improper subdivisions, vehicular access problems, and structures that encroach onto the property after the buyer takes ownership. One of the most important added benefits is post-policy forgery protection. A standard policy generally protects against title issues that existed before the buyer purchased the property. The enhanced policy also provides protection if someone later forges the homeowner’s signature or creates a fraudulent deed that clouds the homeowner’s title. With real estate and identity fraud becoming an increasing concern, this protection alone can provide homeowners with valuable peace of mind. The enhanced policy also includes an automatic increase in coverage. The policy amount increases by 10% each year during the first five years of ownership, up to 150% of the original policy amount. This helps the coverage keep pace as the value of the property increases. In Pennsylvania, the enhanced policy is available for a one-time premium that is only 10% higher than the standard owner’s policy premium, with no annual renewal cost. At Abstract Associates, we believe buyers should understand the difference between the two policies before making their decision. For a relatively small additional cost at settlement, the enhanced policy provides broader protection that can continue to benefit the homeowner long after closing.

Top 10 Things People Don’t Understand About Property Insurance
Most people think of a reverse mortgage as a way for homeowners to access the equity they've built in their current home. While that's certainly true, many Realtors are surprised to learn that a reverse mortgage can also be used to purchase a new home. What Is a Reverse Mortgage? A reverse mortgage, also known as a Home Equity Conversion Mortgage (HECM), is an FHA-insured loan available to homeowners age 62 and older. Instead of making monthly mortgage payments, eligible borrowers can use a portion of their home's equity to eliminate an existing mortgage, establish a line of credit, receive monthly payments, or simply improve cash flow. Borrowers remain responsible for paying property taxes, homeowners' insurance, maintaining the home, and continuing to occupy it as their primary residence. What Is a Reverse Mortgage for Purchase? A HECM for Purchase allows qualified buyers age 55 and older to purchase a new primary residence using a substantial down payment and a reverse mortgage—without the obligation of monthly principal and interest payments.* This program can be an excellent solution for: Buyers looking to downsize. Retirees relocating closer to family. Homeowners moving into a 55+ community. Clients seeking a home that better fits their retirement lifestyle. Buyers who want to preserve more of their retirement savings or investment assets. Instead of paying all cash for a home, buyers can finance part of the purchase through a reverse mortgage, allowing them to keep more of their liquid assets available for future needs. Why Realtors Should Know About This Program A Reverse Mortgage for Purchase can help clients: Increase purchasing power. Improve monthly cash flow. Preserve retirement savings. Purchase a home that better meets their long-term needs. Age in place more comfortably. For many older buyers, this financing option can make the difference between settling for a home and purchasing the one that truly fits their retirement goals. If you work with clients who are 55 or older, a Reverse Mortgage for Purchase may be worth exploring before they write an offer. *Borrowers must continue to pay property taxes, homeowners insurance, maintain the property, and occupy the home as their primary residence. The amount available depends on factors including the youngest borrower's age, current interest rates, and the home's value. Facts, opinions and information expressed in the Blog represent the work of the author and are believed to be accurate but are not guaranteed. The Lancaster County Association of Realtors is not liable for any potential errors, omissions or outdated information. If errors are noted within a post, please notify the Association. Posts represent the author's opinion and are not necessarily the opinion of the Association.