Professional VS Personal Social Media

Althea Ramsay Carrigan, High Associates LTD. • December 19, 2025

Many of us enjoy social media in varied and assorted ways. As I write this we (as a nation) are commemorating the 24th anniversary of September 11 and are also inundated with terrible news about the murder of a young conservative activist, war in the middle east and another school shooting.


Across my newsfeed came “Breaking News” which was an article about a School District of Lancaster teacher who posted some very specific political views on her chosen platform of “X” and/or Facebook which had gone viral and blown back on SDOL.


It made me think of the ways that we as Realtors specifically use social media and the possible implications for our firms, colleagues and livelihoods.


I asked Chat GPT about the early days of social media to see if it matched my understanding as an older person who lived through the it from the beginning. I recall polarized political groups, domestic topics like food/kittens-puppies/family sharing, hobby sites like technology/music/gaming, religion dedicated interaction and of course dating.


Chat GPT says:

  • The early emphasis for social media in America was on enabling digital communication and connection from a distance. The initial intent was to help people interact with friends, family, and like-minded individuals online. Key aspects of early social media in America:
  • Accessible communication: The first websites and software programs were designed to make communication easy and accessible from afar. In the 1970s and 1980s, bulletin board systems (BBSs) allowed users to exchange information in a social setting.
  • Networking and community building: The foundational social media platforms focused on creating online communities and building social networks. Platforms like Classmates.com (1995) helped people connect with school affiliates, while Six Degrees (1997) was the first true social network to allow users to create profiles and list friends.
  • User-driven interaction: Early platforms were built to facilitate genuine, reciprocal relationships. Blogging sites like LiveJournal (1999) and forums allowed users to share personal information and ideas, with features like comments that encouraged community engagement.
  • Interest-based connection: Early platforms created spaces for people with shared interests to gather online. BBS networks developed to serve specific groups and interests, from hobbies to social and political commitments.
  • User-centric experience: The design of early sites like My Space (2003) centered on the user experience by allowing extensive profile customization with music and videos.


Today of course, we see the evolved result of those early platforms that are as different from the origins of interacting as comparing dial-up modems on a computer the size of your desk to our handheld/ear worn/watch face devices with the magically invisible connections. Yesterday my friend warned me about the camera on my desktop watching me and I already knew my phone was listening… but I digress.


Today as professionals we must be cognizant of what we put out there. It can never be taken back. Even more extreme than the happy birthday card that you doodle on and send to your friend today that may be saved in a book and brought out as evidence of that friendship-which you may want to deny in 20 years… We craft the image ourselves today that will exist in cyberspace forever.


Unless you are a master disguiser (and there is no guarantee that your anonymity will last) your clients, prospects and employers can all see the content that you post and use to define yourself. To a great many, you will be and are that person as you appear on-line and that is all (and the best) that they will ever know of you.


As has often been attributed to Will Rogers, the quote “You don’t get a second chance to make a first impression” may ring truest when it comes to someone looking you up on-line before meeting you in person. As freedom of speech is a sacred institution in our country, the right to do (or post) something is different from the wisdom of doing it.


I see Realtors and affiliates in our industry posting and sharing very opinionated content and I often think to myself “Wow, they potentially lost a few clients right there with that one” but of course they have every right to their opinion AND every right to be ok with offending people that they obviously don’t want to associate or collaborate with or to do business with. I also cringe sometimes at angry comments and polarizing views shared from behind a keyboard about people in public service and about our communities. You may disagree with the philosophy, but I believe Realtors should support and help to grow all neighborhoods.


Social media has helped to build careers, launch businesses and start new industries.

It can be harnessed to promote, lift, encourage and attract.


As we continue to evolve with the changing times we must remember to care for the image and the projection of ourselves, our brokerages and the industry we serve. Can we do that while remaining true to ourselves and our beliefs? It was said, as far back as the Bible “Intelligent people think before they speak” and it is as worthwhile today as it was back before there was any way for anyone else to hear what you said except the people with you in your thrush-roofed hut.
By Raquelle Riti, Bernieri Associates Allstate Insurance • November 5, 2026
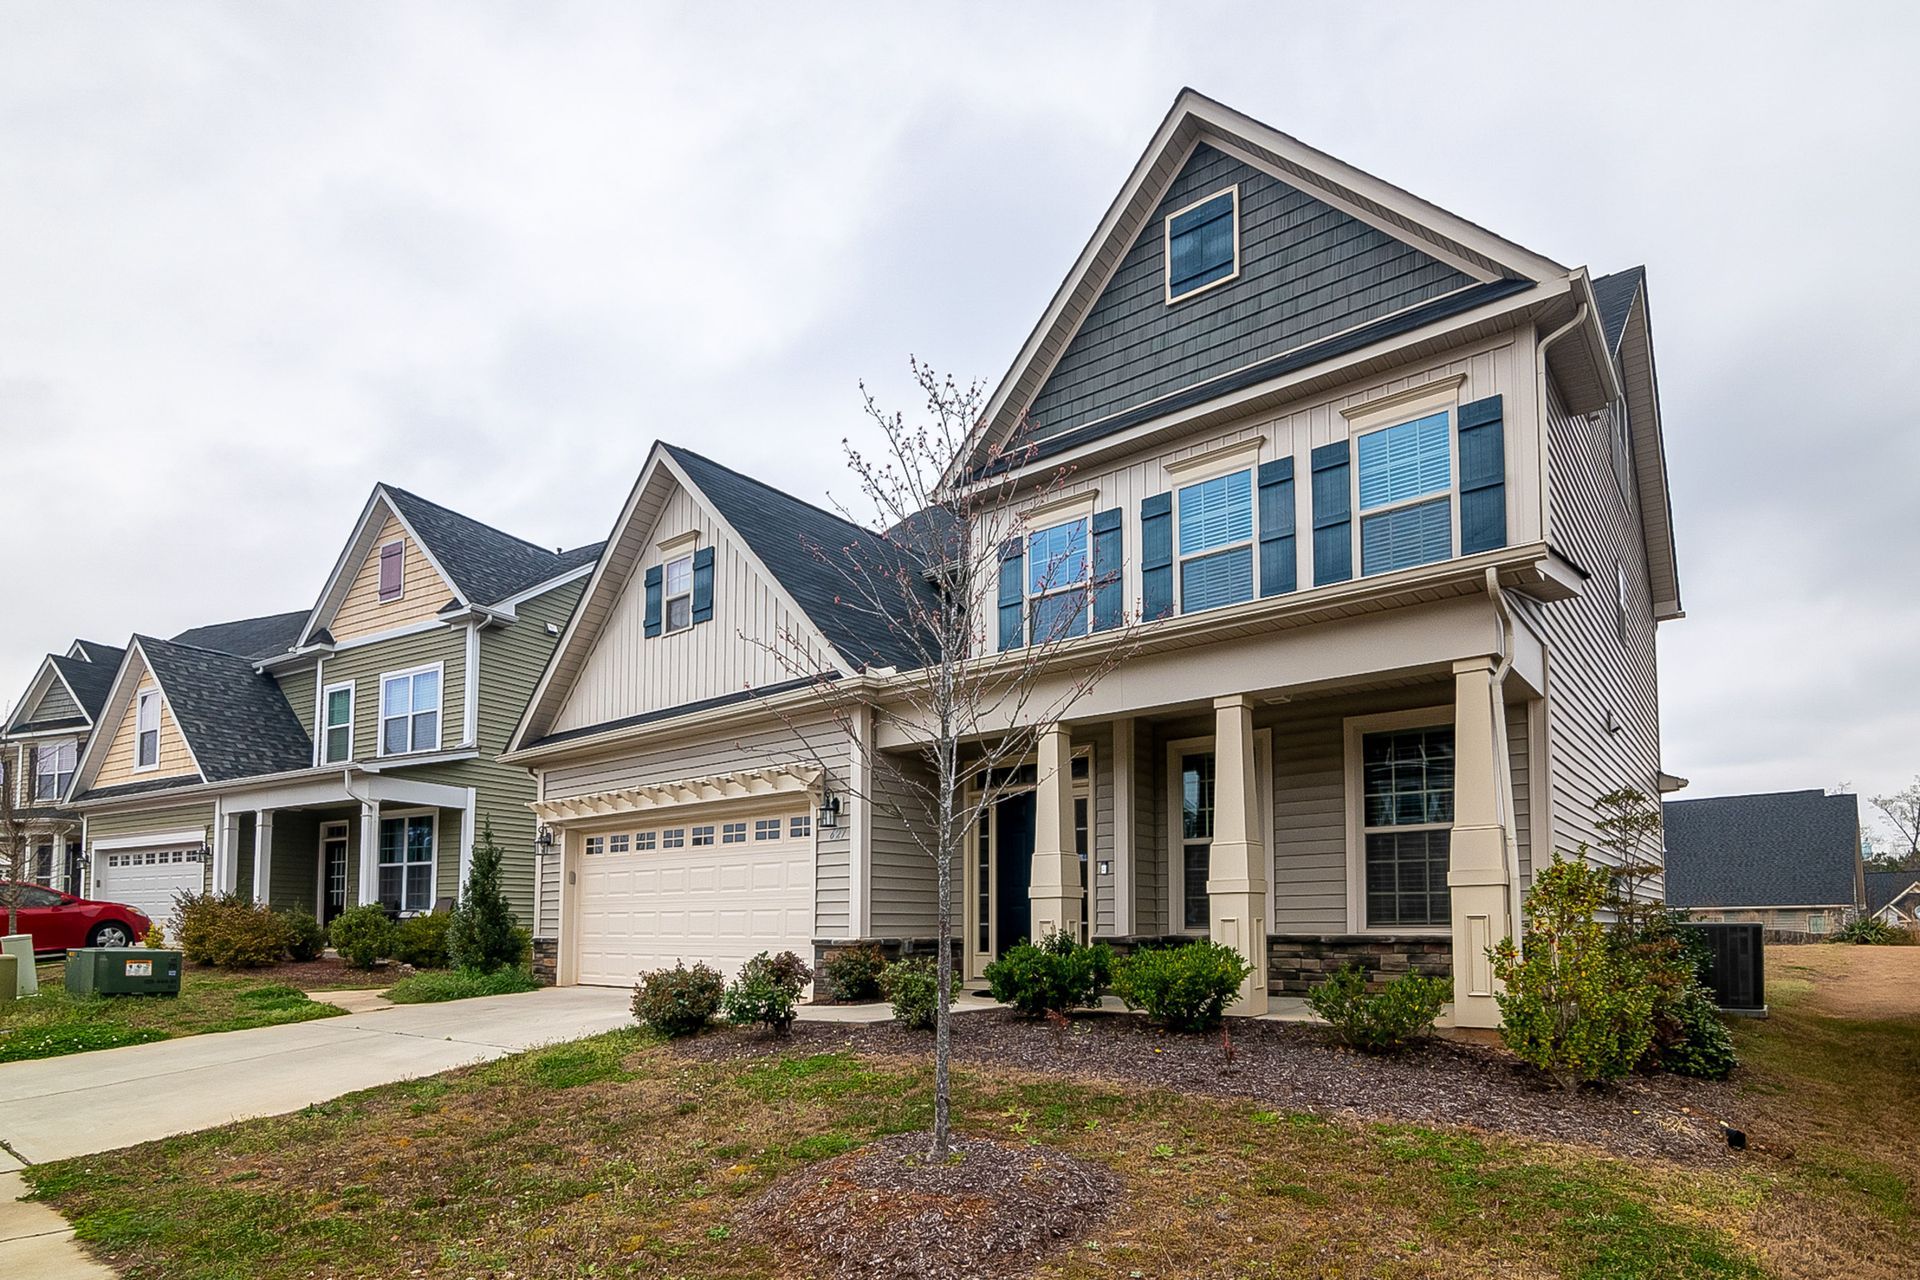
Property insurance is one of those things most people don’t think much about—until they need it. And when a claim happens, the last thing you want is to discover that your policy doesn’t work the way you thought it did. After years of helping homeowners understand their coverage, these are 10 of the biggest misconceptions I see. 1. Your home’s market value is NOT the same as its replacement cost. If you bought your home for $400,000, that doesn’t necessarily mean it should be insured for $400,000. Your home’s replacement cost is based on what it would cost to rebuild the structure with today’s labor and material costs—not what you could sell the property for. Your purchase price also includes things like the land and location. 2. Flood damage usually isn’t covered by homeowners insurance. This is a BIG one. A standard homeowners policy generally does not cover flooding from rising or overflowing water. Flood insurance is typically a separate policy. And no—you don’t necessarily have to live in a high-risk flood zone to experience a flood. 3. Homeowners insurance isn’t a home warranty. Insurance is designed for sudden and accidental losses, not everything that breaks in your house. If your 20-year-old water heater simply reaches the end of its life and stops working, homeowners insurance generally isn’t going to buy you a new one. If that water heater suddenly bursts and causes covered water damage, however, the resulting damage may be a different story. 4. Your deductible is what YOU agree to pay toward a covered claim. If you have a $2,500 deductible and experience a covered $10,000 loss, you shouldn’t expect the insurance company to simply hand you $10,000. Understanding your deductible before you have a claim is incredibly important. Choose an amount that helps with your premium but that you could also realistically afford if something happened tomorrow. 5. Not all water damage is treated the same. “I have water damage” doesn’t automatically tell us whether something is covered. A sudden pipe burst, water backing up through a drain, groundwater entering a basement, and a slow leak that has been happening for months can all be treated differently. Where the water came from and how the damage happened matter. 6. Your belongings have limits, too. Your policy may include personal property coverage for things like furniture, clothing and electronics, but certain categories of property can have special limits. Jewelry, watches, collectibles, firearms, fine art and other high-value belongings may need additional coverage or to be specifically scheduled on the policy. If you own something valuable, tell your insurance agent about it before something happens to it. 7. “Full coverage” isn’t really an insurance coverage. People use the phrase “full coverage” all the time, but there is no magical policy that covers absolutely everything. Every insurance policy has coverage limits, exclusions, deductibles and conditions. The goal isn’t to find a policy that covers every possible scenario to understand what protection you actually have. 8. Your insurance company needs to know about major changes to your home. Finished your basement? Added a pool? Built an addition? Started renting the property? Made significant renovations? Those are things you should discuss with your insurance agent. Your policy was written based on certain information about your home and how it is being used. When that changes, your insurance may need to change with it. 9. The cheapest homeowners policy isn’t always the best deal. Saving money is important, I get it! But two policies with similar premiums can provide very different protection. Before choosing a policy based solely on price, compare things like: Dwelling coverage, Deductibles, Liability limits, Personal property coverage, Water backup coverage, Replacement cost provisions, and Additional endorsements and exclusions. Saving a few hundred dollars a year may not feel like a bargain if you discover a major coverage difference after a loss. 10. The BEST time to understand your policy is before you have a claim. Please don’t wait until there’s water in your basement, a tree on your roof or a fire in your kitchen to learn what your policy covers. Ask questions. Review your coverage. Tell your agent when something changes. Insurance can feel complicated, but that’s exactly why having an agent you trust matters.
Real estate financing and non-mortgage contingent offers explained, including the differences
By Wayne Angelo, Cross Country Mortgage • October 26, 2026
Learn how non-mortgage contingent offers differ from cash offers and what buyers and REALTORS® should know about financing, appraisals, and contract risks.
October 12, 2026
LANCASTER, PA – Lancaster County's housing market continued to show strength in September 2026, with rising home prices, increased inventory, and stronger year-over-year sales activity, according to the latest statistics from Bright MLS. The median sold price reached $370,000, a 4.2% increase from September 2025. A total of 457 homes were sold during the month, up 6.5% from the previous year. Housing inventory also improved, with 779 active listings, an increase of 17.3% compared to September 2025. New listings rose 4.8% to 551 properties, providing buyers with additional opportunities. “Lancaster County continues to demonstrate the strength and stability of our local housing market,” said Christina Diehl, President of the Lancaster County Association of REALTORS® (LCAR). “The increase in available homes is encouraging for buyers, while continued price appreciation reflects the strong demand for housing in our community.” Homes continued to sell quickly, spending an average of just 20 days on the market, compared to 25 days a year earlier. Properties also sold at an average of 103.1% of their original listing price, demonstrating continued competition among buyers. Year-to-date figures remain positive, with closed sales increasing 2.7% and the median sold price rising 4.3% to $365,000. “As we enter the final months of 2026, we remain optimistic about Lancaster County's housing market,” Diehl added. “While increased inventory offers buyers more choices, demand remains strong. Working with a knowledgeable local REALTOR® continues to be an important advantage for both buyers and sellers.” About the Lancaster County Association of REALTORS® The Lancaster County Association of REALTORS® (LCAR) represents real estate professionals throughout Lancaster County and is dedicated to promoting homeownership, protecting private property rights, and supporting professionalism in the real estate industry. 
Father holding son showing work life balance as a realtor
By Wayne Angelo, Cross Country Mortgage • September 28, 2026
Work Life Balance
Time blocking as a real estate agent
By Wayne Angelo, Cross Country Mortgage • September 21, 2026
Time Blocking
REALTOR® using the FOREWARN safety app to verify prospective clients and review available public-rec
By Lisa Naples Berkshire Hathaway HomeServices Homesale Realty • September 14, 2026
Learn how REALTORS® can use FOREWARN to verify prospective clients, review available public records, and add another layer of safety before meeting new contacts.
Enhanced Title Insurance: More Protection for Your Home
By Wayne Angelo, Cross Country Mortgage and Bill Stull, Abstract Associates of Lancaster • August 17, 2026
When purchasing a home, buyers often have the option of choosing either a standard or enhanced owner’s title insurance policy. Both policies protect the buyer’s ownership interest in the property, but the enhanced policy provides several valuable protections that go beyond the coverage included in a standard policy. The enhanced policy is available for purchases of one-to-four-family residences and condominiums when the property is being purchased in an individual’s name, rather than in the name of an LLC, corporation, partnership, or other entity. A standard owner’s policy protects against common title problems, including defects, liens or claims against the property, an unmarketable title, and a lack of legal access. The enhanced policy includes those protections while adding coverage for issues that are especially relevant to homeowners, including certain building permit and zoning violations, improper subdivisions, vehicular access problems, and structures that encroach onto the property after the buyer takes ownership. One of the most important added benefits is post-policy forgery protection. A standard policy generally protects against title issues that existed before the buyer purchased the property. The enhanced policy also provides protection if someone later forges the homeowner’s signature or creates a fraudulent deed that clouds the homeowner’s title. With real estate and identity fraud becoming an increasing concern, this protection alone can provide homeowners with valuable peace of mind. The enhanced policy also includes an automatic increase in coverage. The policy amount increases by 10% each year during the first five years of ownership, up to 150% of the original policy amount. This helps the coverage keep pace as the value of the property increases. In Pennsylvania, the enhanced policy is available for a one-time premium that is only 10% higher than the standard owner’s policy premium, with no annual renewal cost. At Abstract Associates, we believe buyers should understand the difference between the two policies before making their decision. For a relatively small additional cost at settlement, the enhanced policy provides broader protection that can continue to benefit the homeowner long after closing.
Top 10 Things People Don’t Understand About Property Insurance
By Raquelle Riti, Bernieri Associates Allstate Insurance • August 3, 2026
Top 10 Things People Don’t Understand About Property Insurance