Showing Homes: The Details That Matter

Lisa Naples, Berkshire Hathaway HomeServices Homesale Realty • February 20, 2026

You have your real estate license, your BrightMLS membership, your Supra eKey, your ShowingTime account and your signed Buyer Agency Agreement. You’re ready to show some homes!


All you have to do is unlock a door and let your clients in. What could be so hard about this? Some buyers may feel like this is all you’re doing, but we know there is so much more going on, right?


At a bare minimum, you need to make sure you read the showing instructions provided by the listing agent in ShowingTime and read the agent remarks in Bright. Pro tip: Print out the MLS sheet and write the instructions on it. If showing multiple homes, print them all, put them in order of your showings, write the start and end times of each showing and write the agents instructions on each page. Is that too old school? Maybe. But I like to have the info right in front of me and not have to fumble on my phone looking for instructions, combos and lockbox locations.


If you don’t read the instructions and make notes, you may miss that there is an alarm that you have to disarm. If you don’t have this information in front of you, you may not have time to look up the instructions on your phone before the cops show up.


Sometimes agents are early and sometimes they are late. You should notify the listing agent or ShowingTime if your timing is changing.


Continuing with the bare minimum duties, you should follow the instructions of whether or not to turn lights off. If no instructions are provided, then turn off any lights you turn on. You can also reach out to the listing agent if you have questions. If you open an exterior door, make sure it is closed and locked before leaving. Your clients are taking the house in and they are not typically concerned about locking doors or turning lights off, so you need to follow them around and take care of this.


Pro-tip: Don’t open blinds. Too often they are not installed well, and they could come crashing down. Just peak through, lift them away from the window if you want to look at the window, but don’t pull on the cord.


Don’t adjust the thermostat. Thermostats can be surprisingly complicated and hitting the buttons can cause problems. You may accidentally leave the home at an extreme hot temperature, or you may turn the system off during a deep freeze. Just don’t touch it and advise your clients not to touch it.


It’s best not to use the bathroom during a showing. Sometimes the water is turned off and then you’re leaving an unflushed mess. Even if the water is on, things can happen, toilets can get clogged, people can be messy.


If your client’s 5-year-old decides it’s time to go, you can’t easily stop it, so just check the bathroom when they’re finished. Don’t leave a mess, and if there is a mess, let the listing agent know what happened.


Sometimes things break. I’ve seen pictures knocked off the wall with a shoulder, I’ve seen front doors forced open and I’ve definitely seen blinds pulled down. I even had a prospective buyer back into my seller’s car. Anything out of the ordinary should be reported to the listing agent to figure out who is responsible for damages.


If you’re curious if there is hardwood under the carpet, ask the listing agent or look in closets to see if you can find exposed wood. Don’t pull the carpet up from the carpet tack strips. Don’t pull loose wallpaper off the wall. These things happen, especially in vacant homes and they should not. If something looks damaged, don’t poke it and make it worse. Use your eyes, not your hands.


When leaving, make sure the exterior doors are locked and if all the lights are supposed to be off, make sure they’re off. I know buyers can be distracting and you’re trying to manage all of these tasks and answer their questions, give your feedback, get their feedback. But take a moment to secure the home. The most common complaint I get is that the agent left the door unlocked when they left.


Give feedback to the listing agent after the showing. Just a little something is fine, the sellers want it, the agent wants it, it’s part of the process.


What can you do as a listing agent to prevent this stuff? You may consider calling or messaging showing agents before their showing if there is something very critical to note, like an alarm, or an annoyed seller because agents keep leaving the door unlocked. And warn your sellers before the showing process begins.

Let them know that common annoyances to expect are lights being left on when they are not supposed to be on and doors being left unlocked. That agents can be early or late. Basically, the whole process is incredibly inconvenient for the seller, so make sure they know that you know this and you prepare them for it.


One more pro-tip for listing agents: Put the key on a key fob when you put it in the lockbox. A key without a key fob when dropped can bounce into the landscaping and be lost forever (true story), or it can slip into a 4-inch-deep crack between the house and the sidewalk (true story) or it can be forgotten in a pocket and taken away (true story).


One last pro-tip: You are a professional door opener. Don’t let the lock get the best of you. You need to be able to jiggle and finagle locks, not all of them are easy. Don’t give up. And know that some door handles have to be lifted up in order to lock the door. And sometimes there are toe-kick locks or high locks on sliding doors, don’t try to force it if it’s not moving, check for these locks or the old stick in the track. And if a closet door seems stuck, push down on the doorknob when opening, which often releases it from the top. Don’t manhandle it, just use a little finesse.


All of this feedback is based on real life showing issues. When you are showing homes to your client, you are doing a whole lot more than unlocking a door. Don’t forget this.
By Raquelle Riti, Bernieri Associates Allstate Insurance • November 5, 2026
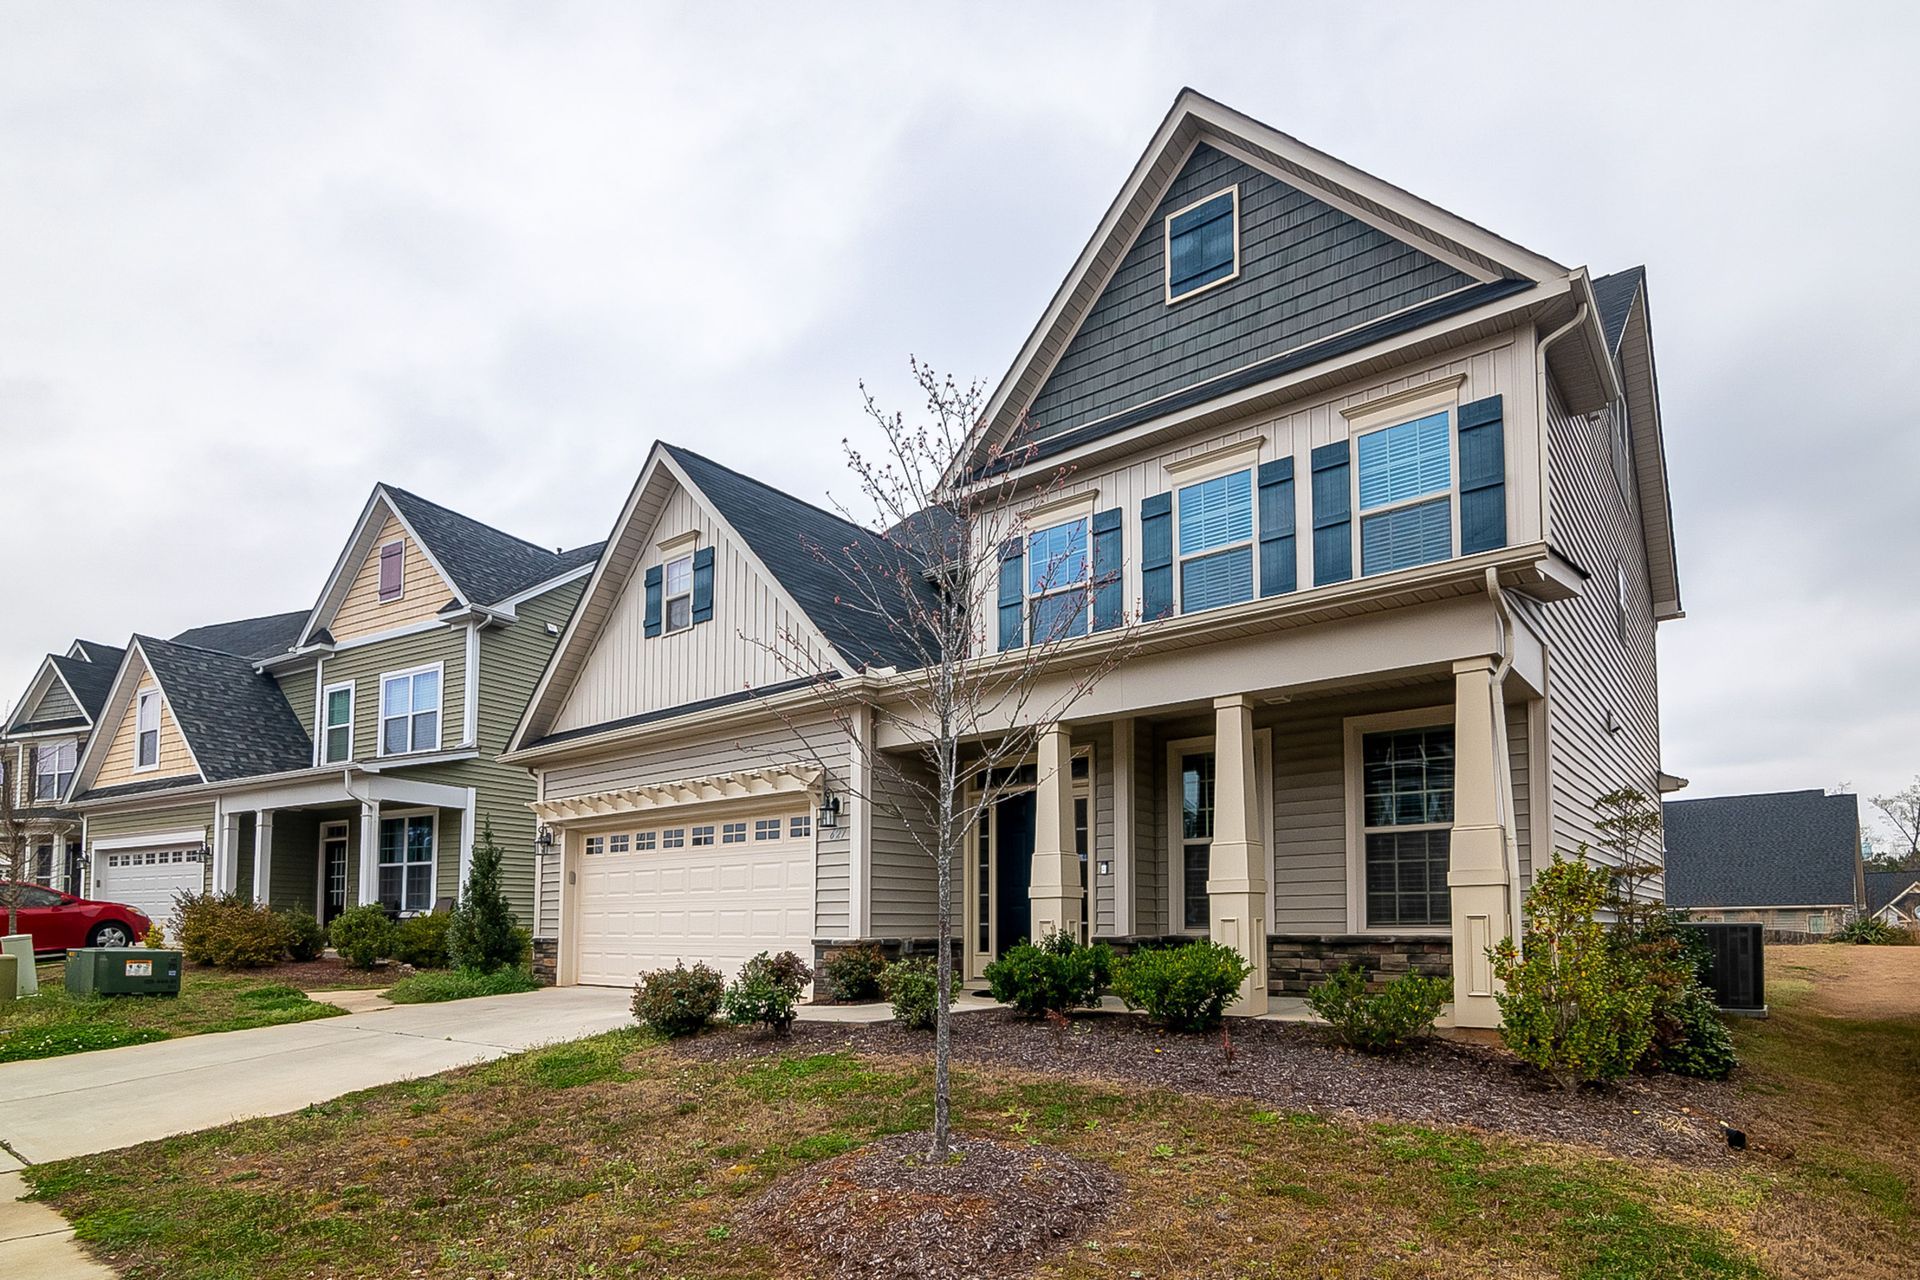
Property insurance is one of those things most people don’t think much about—until they need it. And when a claim happens, the last thing you want is to discover that your policy doesn’t work the way you thought it did. After years of helping homeowners understand their coverage, these are 10 of the biggest misconceptions I see. 1. Your home’s market value is NOT the same as its replacement cost. If you bought your home for $400,000, that doesn’t necessarily mean it should be insured for $400,000. Your home’s replacement cost is based on what it would cost to rebuild the structure with today’s labor and material costs—not what you could sell the property for. Your purchase price also includes things like the land and location. 2. Flood damage usually isn’t covered by homeowners insurance. This is a BIG one. A standard homeowners policy generally does not cover flooding from rising or overflowing water. Flood insurance is typically a separate policy. And no—you don’t necessarily have to live in a high-risk flood zone to experience a flood. 3. Homeowners insurance isn’t a home warranty. Insurance is designed for sudden and accidental losses, not everything that breaks in your house. If your 20-year-old water heater simply reaches the end of its life and stops working, homeowners insurance generally isn’t going to buy you a new one. If that water heater suddenly bursts and causes covered water damage, however, the resulting damage may be a different story. 4. Your deductible is what YOU agree to pay toward a covered claim. If you have a $2,500 deductible and experience a covered $10,000 loss, you shouldn’t expect the insurance company to simply hand you $10,000. Understanding your deductible before you have a claim is incredibly important. Choose an amount that helps with your premium but that you could also realistically afford if something happened tomorrow. 5. Not all water damage is treated the same. “I have water damage” doesn’t automatically tell us whether something is covered. A sudden pipe burst, water backing up through a drain, groundwater entering a basement, and a slow leak that has been happening for months can all be treated differently. Where the water came from and how the damage happened matter. 6. Your belongings have limits, too. Your policy may include personal property coverage for things like furniture, clothing and electronics, but certain categories of property can have special limits. Jewelry, watches, collectibles, firearms, fine art and other high-value belongings may need additional coverage or to be specifically scheduled on the policy. If you own something valuable, tell your insurance agent about it before something happens to it. 7. “Full coverage” isn’t really an insurance coverage. People use the phrase “full coverage” all the time, but there is no magical policy that covers absolutely everything. Every insurance policy has coverage limits, exclusions, deductibles and conditions. The goal isn’t to find a policy that covers every possible scenario to understand what protection you actually have. 8. Your insurance company needs to know about major changes to your home. Finished your basement? Added a pool? Built an addition? Started renting the property? Made significant renovations? Those are things you should discuss with your insurance agent. Your policy was written based on certain information about your home and how it is being used. When that changes, your insurance may need to change with it. 9. The cheapest homeowners policy isn’t always the best deal. Saving money is important, I get it! But two policies with similar premiums can provide very different protection. Before choosing a policy based solely on price, compare things like: Dwelling coverage, Deductibles, Liability limits, Personal property coverage, Water backup coverage, Replacement cost provisions, and Additional endorsements and exclusions. Saving a few hundred dollars a year may not feel like a bargain if you discover a major coverage difference after a loss. 10. The BEST time to understand your policy is before you have a claim. Please don’t wait until there’s water in your basement, a tree on your roof or a fire in your kitchen to learn what your policy covers. Ask questions. Review your coverage. Tell your agent when something changes. Insurance can feel complicated, but that’s exactly why having an agent you trust matters.
Real estate financing and non-mortgage contingent offers explained, including the differences
By Wayne Angelo, Cross Country Mortgage • October 26, 2026
Learn how non-mortgage contingent offers differ from cash offers and what buyers and REALTORS® should know about financing, appraisals, and contract risks.
October 12, 2026
LANCASTER, PA – Lancaster County's housing market continued to show strength in September 2026, with rising home prices, increased inventory, and stronger year-over-year sales activity, according to the latest statistics from Bright MLS. The median sold price reached $370,000, a 4.2% increase from September 2025. A total of 457 homes were sold during the month, up 6.5% from the previous year. Housing inventory also improved, with 779 active listings, an increase of 17.3% compared to September 2025. New listings rose 4.8% to 551 properties, providing buyers with additional opportunities. “Lancaster County continues to demonstrate the strength and stability of our local housing market,” said Christina Diehl, President of the Lancaster County Association of REALTORS® (LCAR). “The increase in available homes is encouraging for buyers, while continued price appreciation reflects the strong demand for housing in our community.” Homes continued to sell quickly, spending an average of just 20 days on the market, compared to 25 days a year earlier. Properties also sold at an average of 103.1% of their original listing price, demonstrating continued competition among buyers. Year-to-date figures remain positive, with closed sales increasing 2.7% and the median sold price rising 4.3% to $365,000. “As we enter the final months of 2026, we remain optimistic about Lancaster County's housing market,” Diehl added. “While increased inventory offers buyers more choices, demand remains strong. Working with a knowledgeable local REALTOR® continues to be an important advantage for both buyers and sellers.” About the Lancaster County Association of REALTORS® The Lancaster County Association of REALTORS® (LCAR) represents real estate professionals throughout Lancaster County and is dedicated to promoting homeownership, protecting private property rights, and supporting professionalism in the real estate industry. 
Father holding son showing work life balance as a realtor
By Wayne Angelo, Cross Country Mortgage • September 28, 2026
Work Life Balance
Time blocking as a real estate agent
By Wayne Angelo, Cross Country Mortgage • September 21, 2026
Time Blocking
REALTOR® using the FOREWARN safety app to verify prospective clients and review available public-rec
By Lisa Naples Berkshire Hathaway HomeServices Homesale Realty • September 14, 2026
Learn how REALTORS® can use FOREWARN to verify prospective clients, review available public records, and add another layer of safety before meeting new contacts.
Enhanced Title Insurance: More Protection for Your Home
By Wayne Angelo, Cross Country Mortgage and Bill Stull, Abstract Associates of Lancaster • August 17, 2026
When purchasing a home, buyers often have the option of choosing either a standard or enhanced owner’s title insurance policy. Both policies protect the buyer’s ownership interest in the property, but the enhanced policy provides several valuable protections that go beyond the coverage included in a standard policy. The enhanced policy is available for purchases of one-to-four-family residences and condominiums when the property is being purchased in an individual’s name, rather than in the name of an LLC, corporation, partnership, or other entity. A standard owner’s policy protects against common title problems, including defects, liens or claims against the property, an unmarketable title, and a lack of legal access. The enhanced policy includes those protections while adding coverage for issues that are especially relevant to homeowners, including certain building permit and zoning violations, improper subdivisions, vehicular access problems, and structures that encroach onto the property after the buyer takes ownership. One of the most important added benefits is post-policy forgery protection. A standard policy generally protects against title issues that existed before the buyer purchased the property. The enhanced policy also provides protection if someone later forges the homeowner’s signature or creates a fraudulent deed that clouds the homeowner’s title. With real estate and identity fraud becoming an increasing concern, this protection alone can provide homeowners with valuable peace of mind. The enhanced policy also includes an automatic increase in coverage. The policy amount increases by 10% each year during the first five years of ownership, up to 150% of the original policy amount. This helps the coverage keep pace as the value of the property increases. In Pennsylvania, the enhanced policy is available for a one-time premium that is only 10% higher than the standard owner’s policy premium, with no annual renewal cost. At Abstract Associates, we believe buyers should understand the difference between the two policies before making their decision. For a relatively small additional cost at settlement, the enhanced policy provides broader protection that can continue to benefit the homeowner long after closing.
Top 10 Things People Don’t Understand About Property Insurance
By Raquelle Riti, Bernieri Associates Allstate Insurance • August 3, 2026
Top 10 Things People Don’t Understand About Property Insurance